Ethiopia holds a special place in coffee history, yet many view it as one of the more complex countries to source coffee from. It has experienced several changes through its history that have affected the marketing of coffee and was a topic of discussion with producers and suppliers during our December 2025 visit. As private companies in Ethiopia continue to flourish, cooperatives are feeling the pinch. In this article, we take a look at some of the complexities and differences on the ground whilst looking back through Ethiopia’s coffee history.
It can be hard to pick a starting point for trade with Ethiopian coffee given, that the country is acknowledged as the birthplace of the drink now consumed the world over. The path to today’s structure can be traced by looking back to the 1950’s when Ethiopia started a journey through a series of changes that would underpin the formations we see today. This was born from the fallout of World War 2, when the United Nations created the Federation of Ethiopia and Eritrea triggering events that culminated in a 30-year insurgency aimed at achieving self-determination and independence for Eritrea from Ethiopian rule.
A short history of the coffee market in Ethiopia
From the early 1950’s coffee in Ethiopia was regulated by a Proclamation. Managed by both the Ministry of Commerce and Industry and the Ministry of Agriculture for differing areas, the key operators in the field were the brokers and collectors that worked in coffee-growing regions and processors preparing the coffee. It was collated into regional sources, designated in the regulations to be called Harari, Arusi, Sidamo, Gimma, Lekempti and Gore. This would change in 1955 to be Harar, Sidamo, Jimma and Lekemti. Coffee was channelled to largely privately-owned auction centres in Dire Dawa and Addis Ababa to be sold to exporters through regular if not daily sales via licensed private companies. Those auction prices paid did not always make their way back to the producers and so pricing signals at farm level were weak.
Multiple practises existed in this system and there was no proper standardisation as auctions had existed before this and grown organically. The law saw repeated updates, and it would cover various facets of the industry from quality, grading and marketing, but nothing was really institutionalised. The dual government departments were replaced in 1957 by the National Coffee Board which had powers to build warehouses and other infrastructure though oversight, not control, was the reality.
This changed in 1972 with the introduction of the Coffee Auction system, providing a central reference price for the coffee and linking domestic prices indirectly to export demand. Coffee would typically be pooled and graded before a sale, which simplified the trade with exporters purchasing almost exclusively through the auctions. This helped in creating standardised procedures, also granting the government better insight into export economics and allowed for taxations to be levied that may have been avoided previously.
Yet further upheaval came in the 70’s with the Ethiopian Revolution and demands for social change and agrarian reforms. These would escalate and by the1980’s insurgencies had escalated into all out wars.
In 1974, Ethiopia became a Marxist state under the Derg, and the auction system introduced in 1972 now fell under a radically different ideological regime than those that founded it. It became highly centralized and state controlled, with prices and flows increasingly influenced by state policy rather than market competition. Large farms also became nationalized.
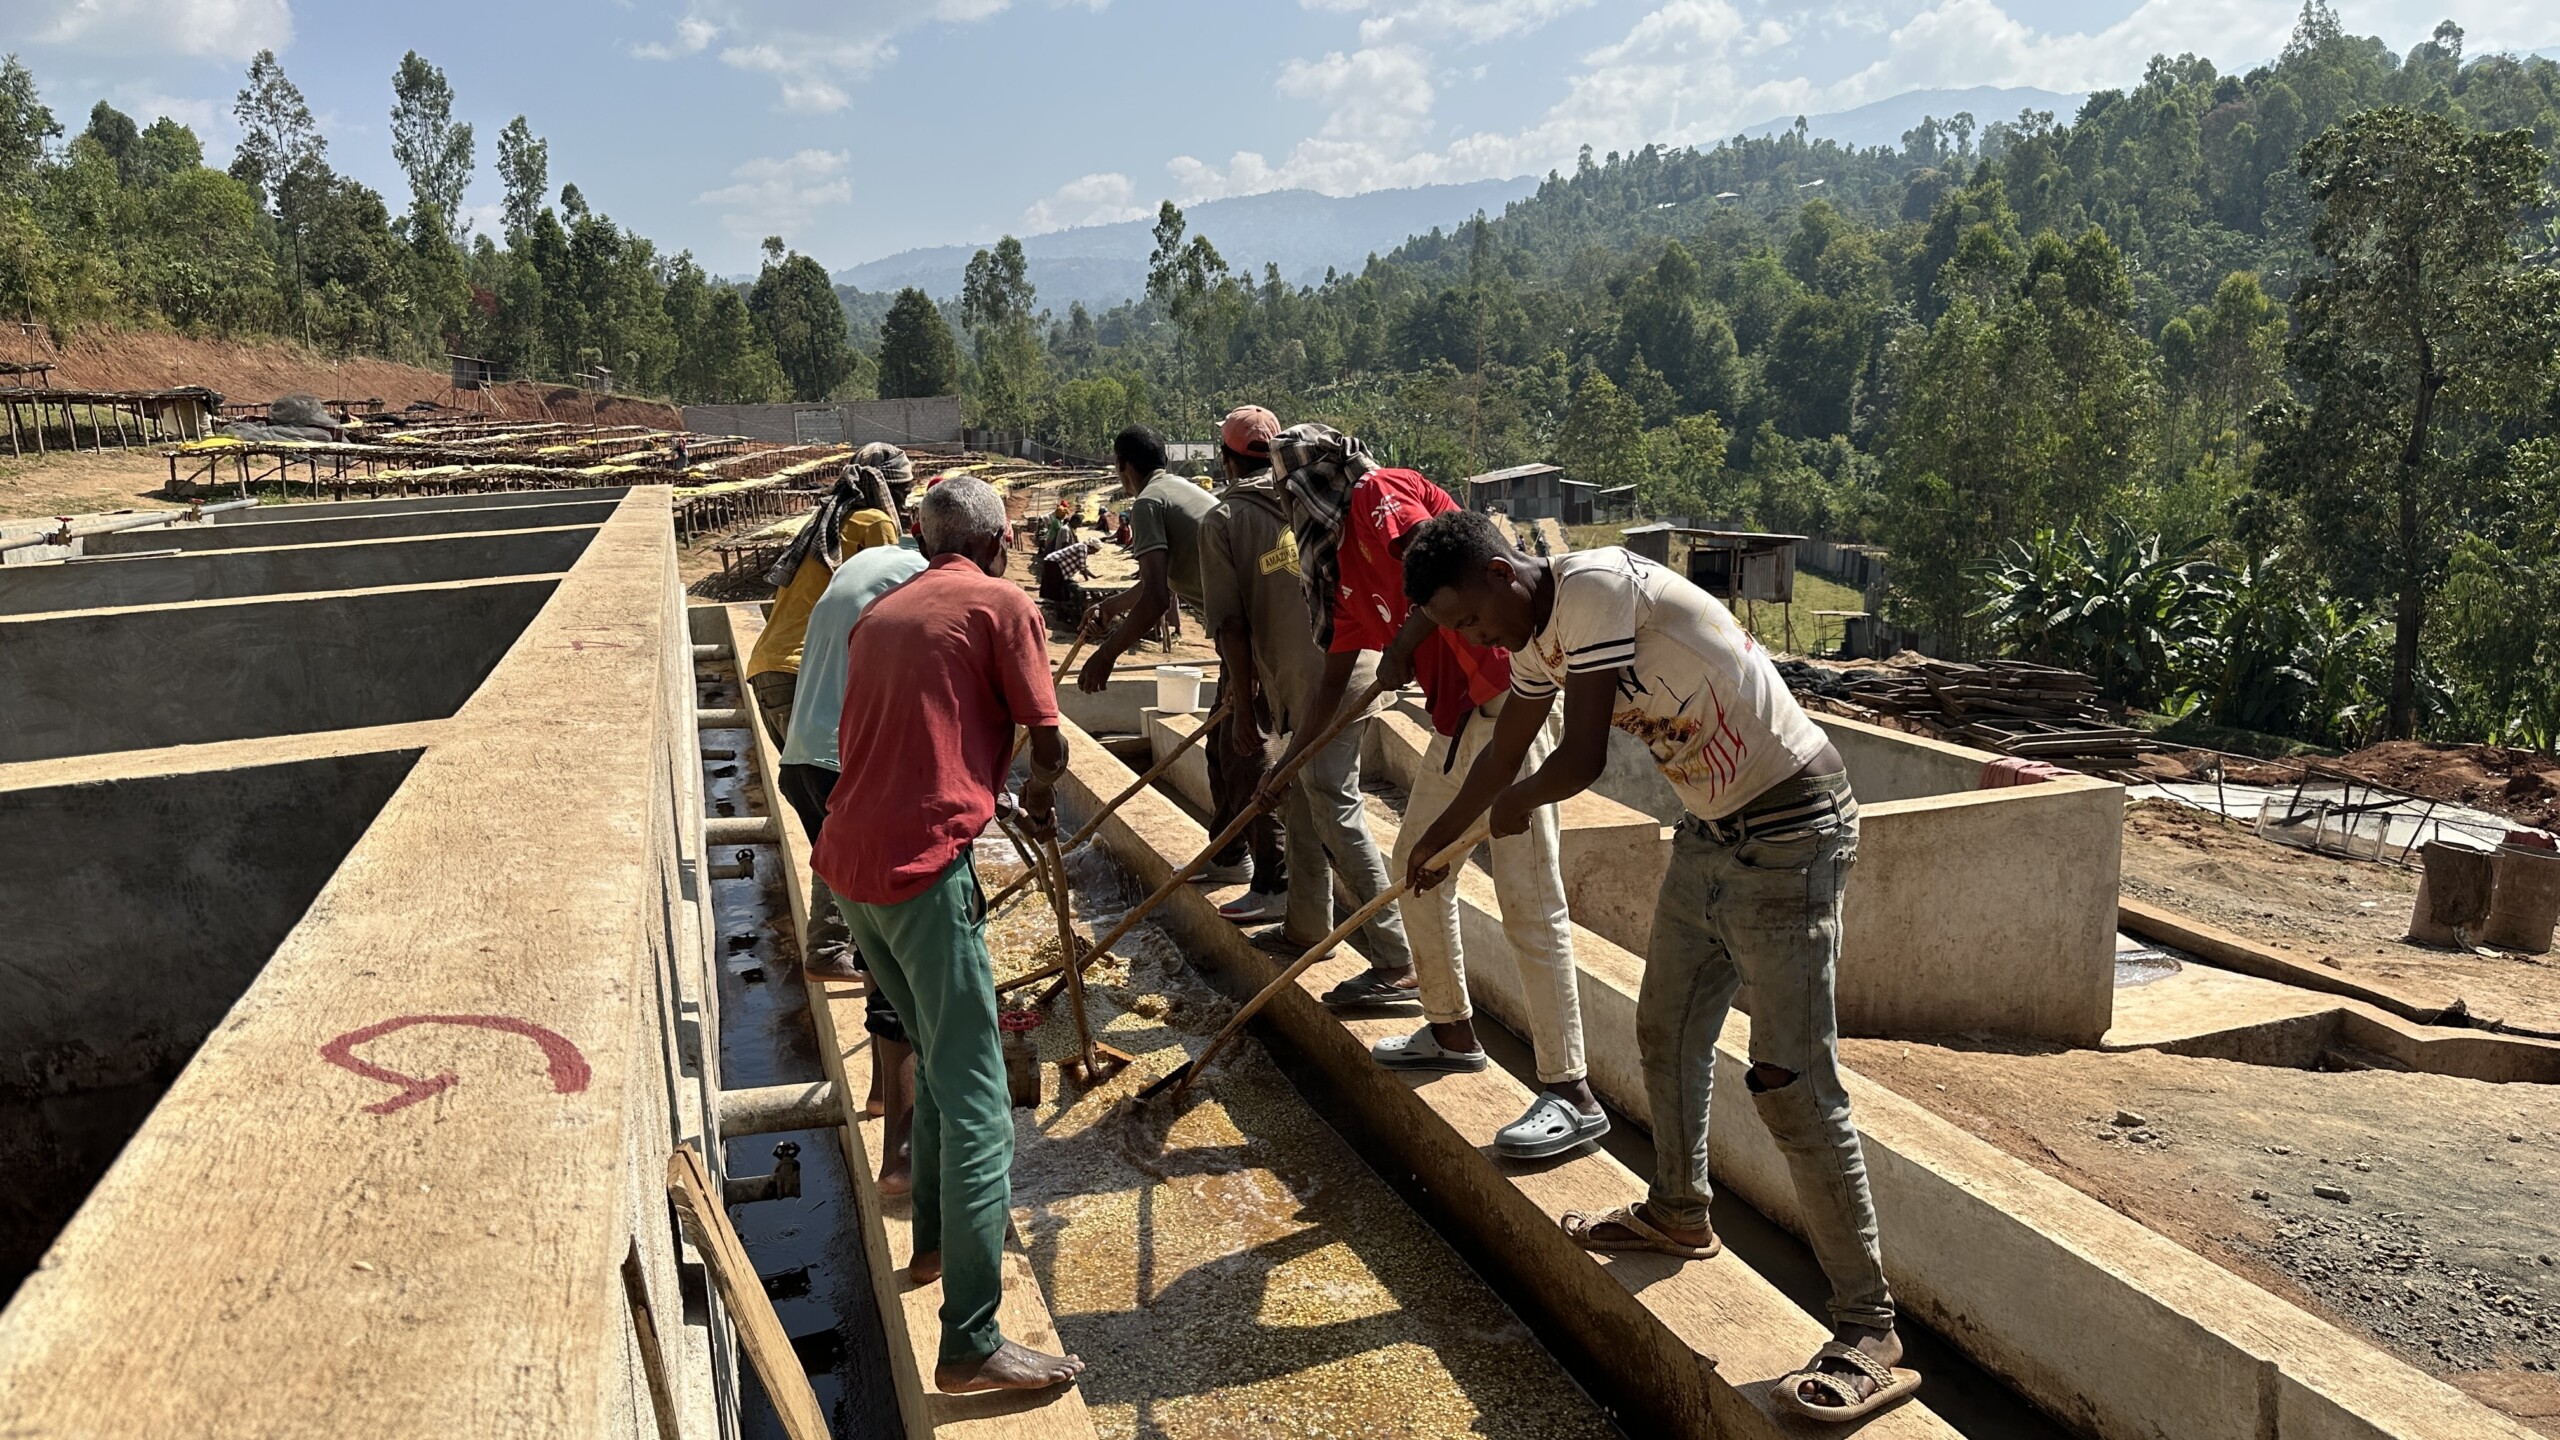
The Cooperative movement
Historically, farmers would deliver coffee to private companies who would only pay for the goods once the coffee was sold/exported. Many of these private companies were Eritrean. In 1983, Eritrean private companies left Ethiopia due to the Independence War, leaving thousands of farmers unpaid – around 60-70% of the total smallholders in the country. This pushed many families into poverty.
Cooperative Unions were born from this to create greater security for smallholder farmers. After 1991, the government allowed coops to form and set fair prices for coffee. Rather than being unpaid until coffee was sold at international market, the risks were absorbed by the Unions who would pay farmers on delivery and distributed dividends at the end of the season. They also took on marketing of coffee internationally.
At the same time, the Coffee Auction system (set up in 1972) was still in place, giving producers an avenue to continue delivering coffee at their own risk. Private companies who still operated would find a market and the producer got paid once coffee was sold. As the cooperative model became more attractive, Unions got bigger and membership increased.
In 2008 the Ethiopian Commodity Exchange (ECX) was introduced to protect smallholders from risk in the auction model. The ECX was managed by the Ethiopian Coffee Authority, who took on responsibility of receiving coffee, looked after warehousing, marketing, quality etc. With the introduction of the ECX came a new list of Ethiopia’s coffee growing areas, defined by agricultural considerations, such as altitude, soil, varietals and farming culture. These were Bale, Bebeka, Harrar (A, B & C), Jimma/Limmu, Kaffa, Lekempt, Sidamo (A, B, C, D & E), Tepi and Yirgacheffe (A & B). It was considered to have modernised the country’s economy and was the only functioning commodity exchange in Africa. This brought stability, but was not a universally accepted progression for sellers, especially those engaging with the speciality market that wanted tighter traceability.
The ECX expanded in 2021 opening opportunities for more direct sales from farmers to market, meaning private companies have come back onto the scene to engage with international markets. The new system has created two types of trade – vertical and horizontal. The vertical model means exporters can source and sell coffee from their own farms and others, while the horizontal model means exporters can sell coffee to other exporters, if they do not have the market to sell to themselves.

In 2025 the Specialty Coffee Association of Ethiopia (SCAE) was set up to improve standards and traceability, expanding market access (e.g., China trade center). As the Ethiopian specialty industry continues to develop, private companies are increasingly better able to compete on price and quality through these models, meaning they are able to offer better internal prices to farmers in comparison to the cooperatives. Cooperative member farmers are gradually selling more coffee to private wet mills for immediate better prices.
At the time of our visit, it was estimated that most cooperative members would sell 50% of coffee to private companies. This avenue of sale had recently driven up the price of coffee cherries, so cooperatives were having to incentivise members to continue working with them, often via prefinance or a premium paid as a dividend after 3-4 months of harvest.
The job of the cooperative today is to convince members of the benefits of the coop system, especially focusing on certification. The benefits of selling to a coop are not as immediate as selling to a private company, however the long-term benefits are significant. This includes community support and engagement, Fairtrade premiums which support social projects such as housing and rod building, and access to seedlings, agronomical training and even prefinance.
The cooperative system, however, still remains strong in Ethiopia. The culture of coffee cooperatives has similarities to the Gada system, an indigenous democratic socio-political governance system of Ethiopia’s Oromo people. The system uses an age-based class structure that rotates leadership every 8 years, much like the rotational management and leadership structure of the cooperative, decided through general assembly.
 WCR Ethiopian Landrace
The Future
With a long legacy of change and development, the future of coffee in Ethiopia looks to continue moving forward at the same. Current governmental funding and land acquisition grants are opening the concept of large-scale mechanised farming to private companies. While genetic development in institutions like the the Jimma Agricultural Research Centre (JARC) introduce specific varietals to the field, focused on higher yields and resistance, such as 74110 and 74111.
As the landscape of coffee cultivation in Ethiopia continues to change, will we see a change to the flavour and quality of Ethiopia’s coffee? Time will tell.