Welcome to DRWakefield’s Weekly Coffee Market Report.
This report touches upon the Arabica and Robusta coffee futures market, currency pairings and news from origin. See our Market Report Terms page for clarity on any terminology in the coffee market report below.
Live Market Data
Coffee Market Report
This report covers the period from Monday 24th August to Friday 28th August and was written by James Duncan and Jamie Treby.
 Arabica (Chart: TradingView)
Market Report
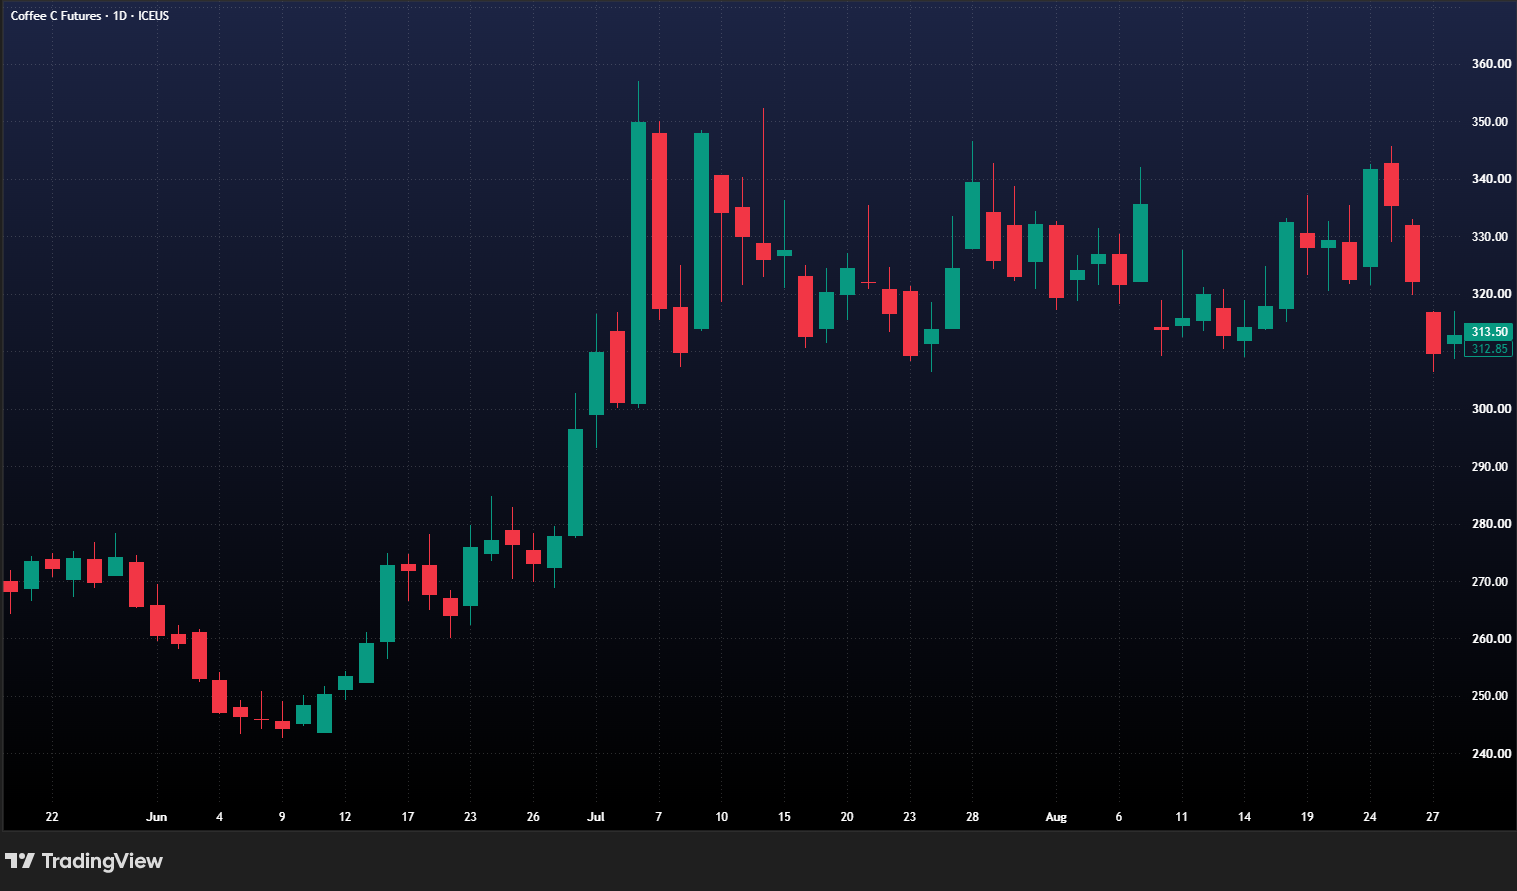
Opening the week at 324.920 usc/lb following a weak flagging towards the end of the previous week, the market rallied +19 usc/lb on Monday 24th August. As is common these days, the market move was mostly technical, with what little fundamental news we have being used as a basis and further amplified. Breaking above 332 triggered origin selling and stop orders which softened the rally, closing just below the daily high (342.55 usc/lb) at 341.65 usc/lb.
Tuesday saw an initial continuation of the rally, hitting the weekly high of 345.65 usc/lb, a technical barrier which triggered profit taking and further origin selling. After this, the market fell back to a low of 329 before recovering to 335.50 usc/lb for close. Wednesday continued the downwards trend, closing 13.35 usc/lb lower at 322.15 usc/lb.
Our largest piece of fundamental news for the week was a correction from Cecafe on Wednesday, which said that instead of running 20% behind July’s exports, Brazil was 20.5% ahead. This was important as August is typically a month of higher exports for Brazil, with fresh crop shipments in full swing. A reduction in exports implied that the harvest was delayed by more than expected (a figure contradicted by harvest figures), or that exporters were withholding stock. Such a stark revision showed that, in fact, fresh crop was proceeding as expected, eradicating any cause for concern.
Off the back of this news, the market opened 5.25 usc/lb lower on Thursday (316.90 usc/lb) and finished 12.50 usc/lb below Wednesday close (309.65 usc/lb) – the lowest close for Dec-26 terminal since the beginning of August. After 3 days of sharp decline, Friday posted sideways movement and reduced volume, closing the week at 312.85 usc/lb: a drop of 12.05 usc/lb from Monday open, and weekly range of 39.20 usc/lb.
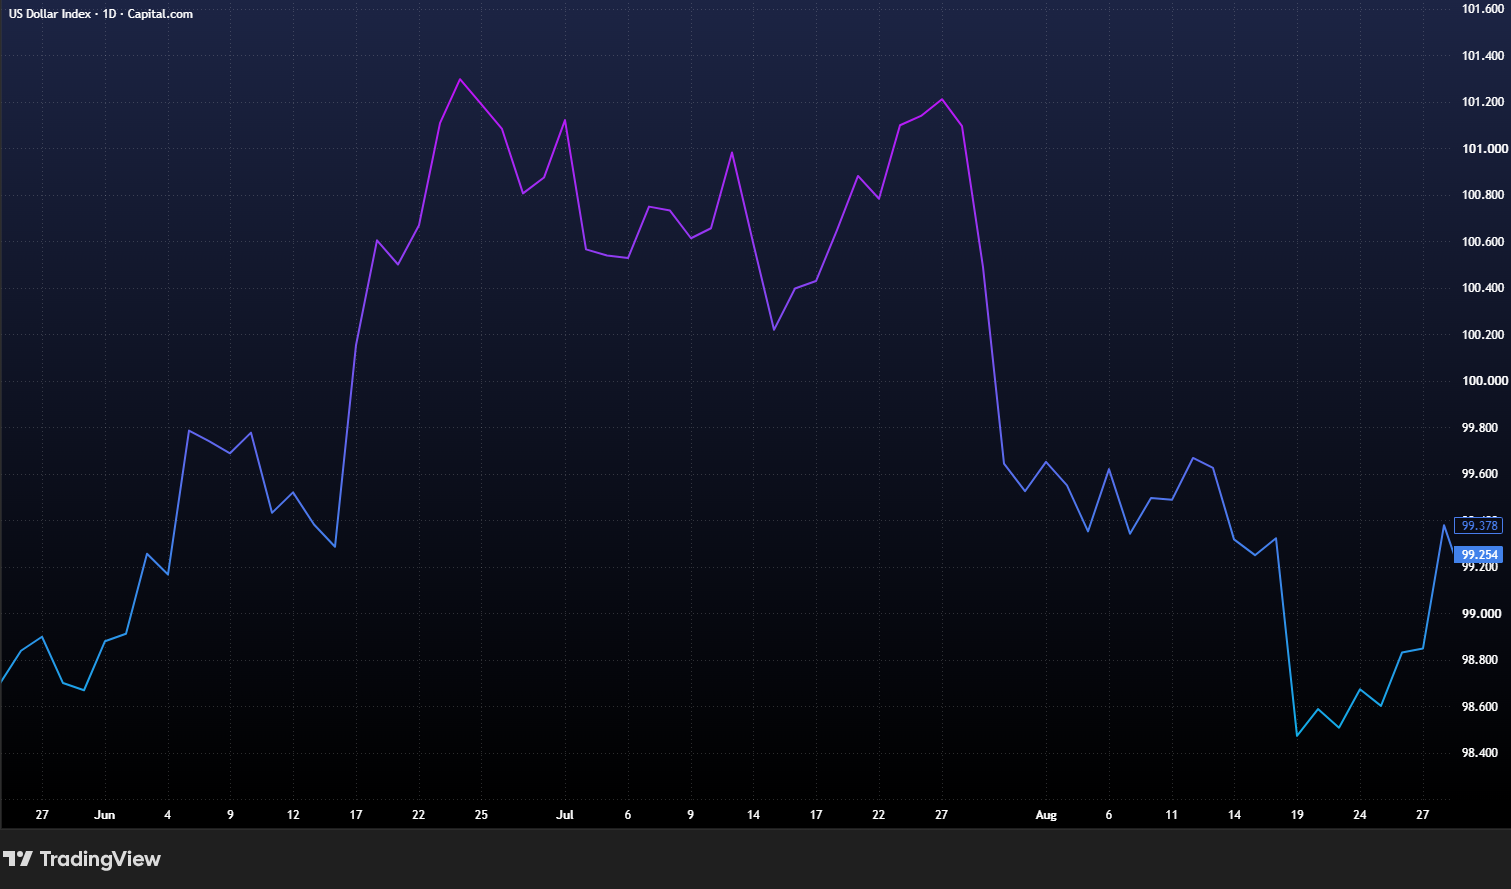 DXY (Chart: TradingView)
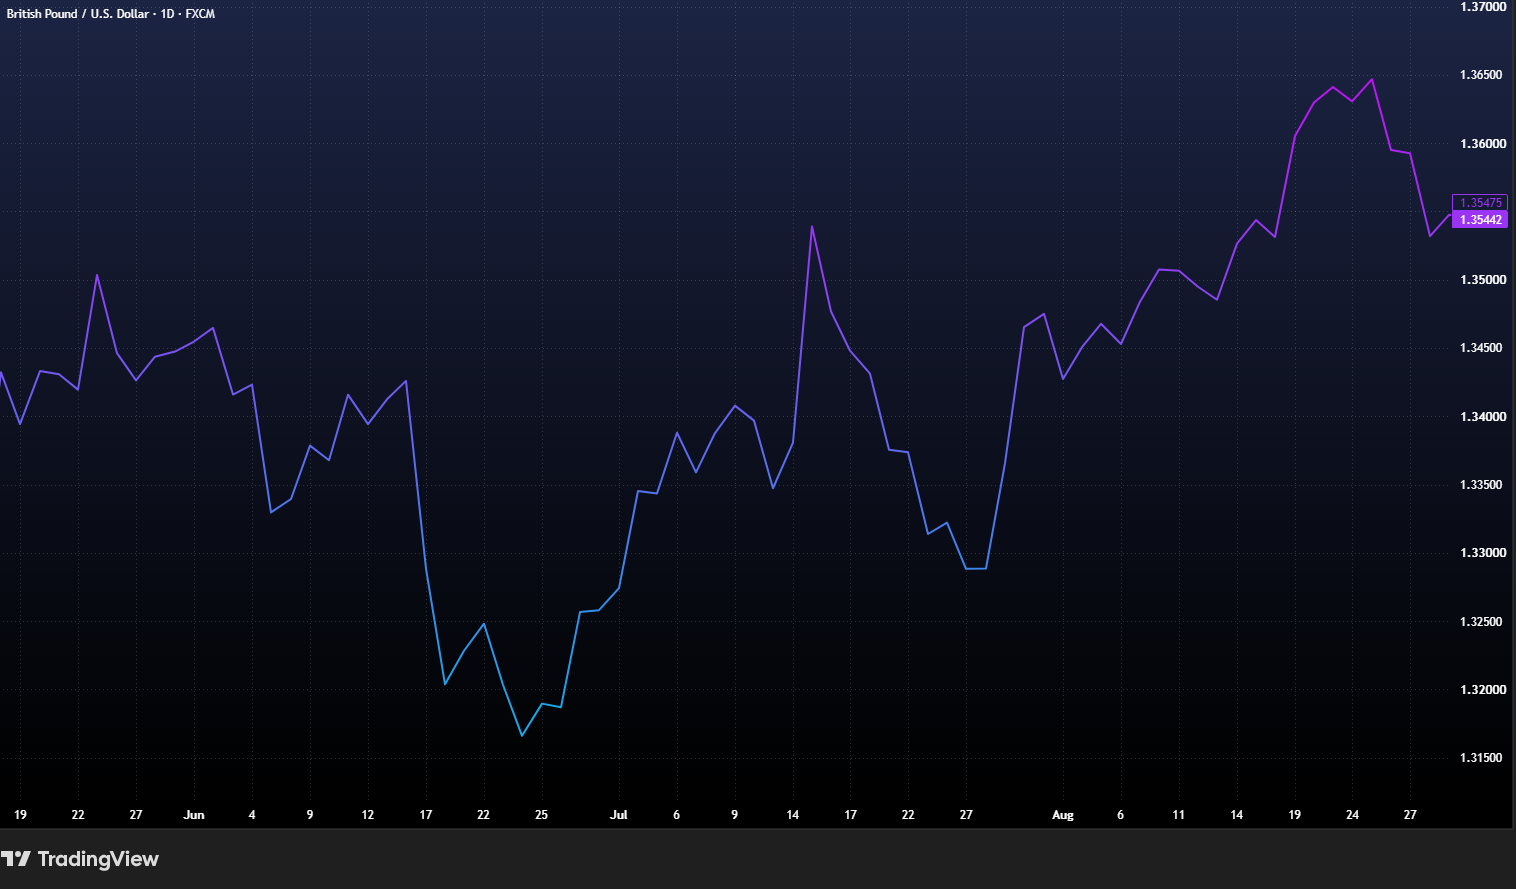 GBP/USD (Chart: TradingView)
Currency & Macro
The period 24th – 28th August was relatively slow on currency and macro news, as is normal around this time of year. Here in the UK, August is sometimes referred to as ‘Silly Season’ given the distinct lack of news: with many employees on holiday, schools and parliament on recess, reporting often turns humorous or frivolous.
This is broadly true for the FX markets this week, with the main news being a strengthening dollar amid broad expectations of hawkish fed. The Dollar Index (DXY) recovered some of its recently losses, climbing from around 99.0 to 99.7, with the GBP/USD and EUR/USD falling 1.364 – 1.354 and 1.166 – 1.159 respectively.
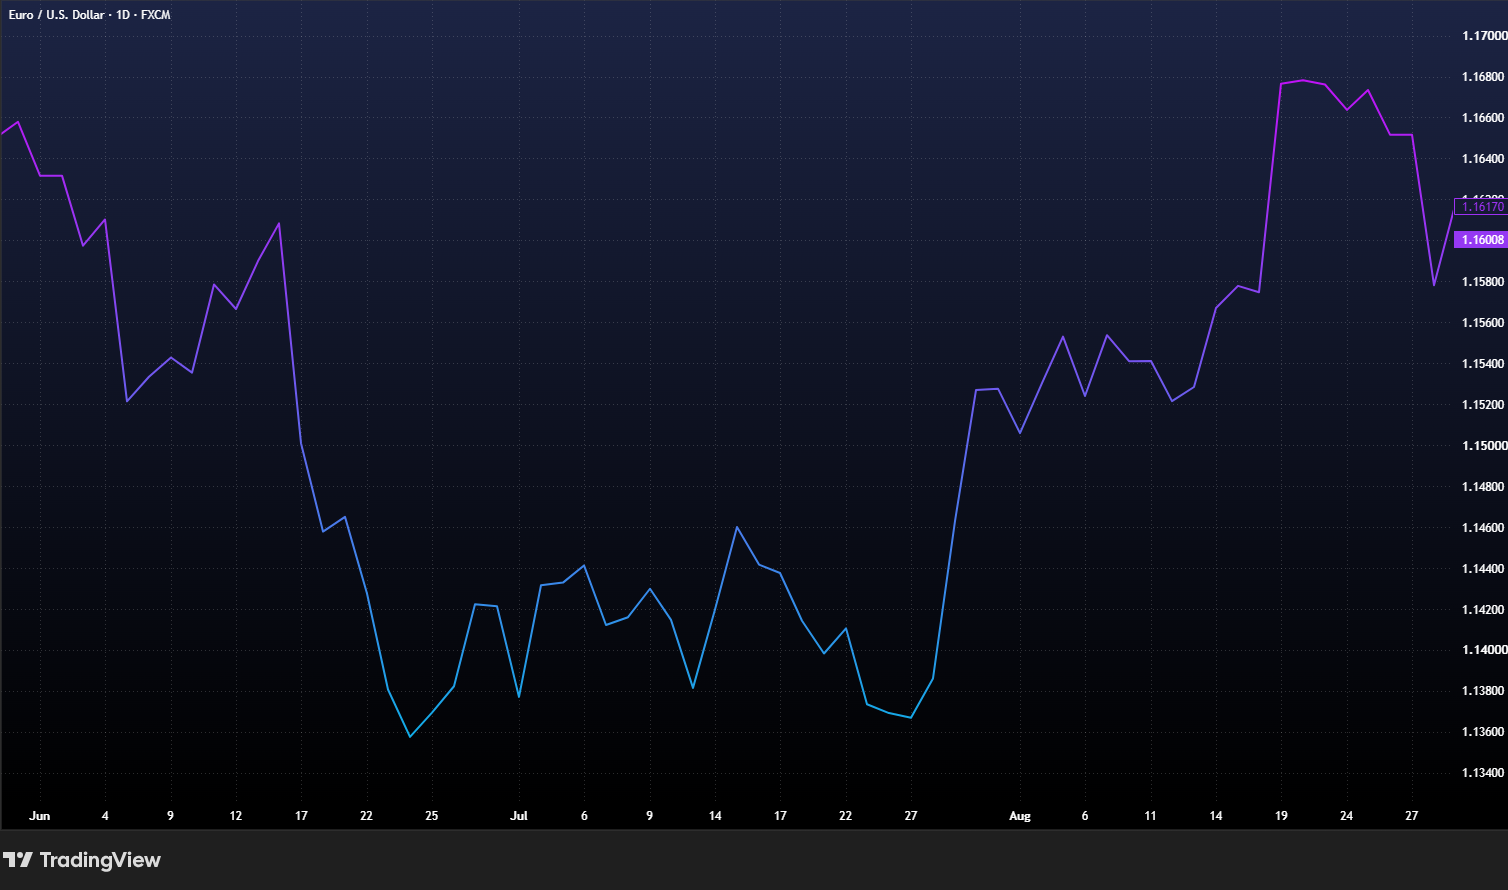 EUR/USD (Chart: TradingView)
Origin
Colombia is still recovering from the recent earthquake, but the coffee harvest was reported to have dodged the impact that hit the western part of the country. In an interview with Reuters just over a week ago, the Head of the National Coffee Growers Federation, German Bahamon, suggested that coffee growers saw the impending El Nino as a bigger threat to the production. The federation is expecting a drop of around 8% caused by El Nino, and the heavy rains that came earlier in the year.
Infrastructure was affected by the quake, with damaged caused across a third of the coffee producing regions. Shipping stopped briefly, but was reported to have returned to normal. However, reality suggests logistics remain slightly behind around 15-30 day delays possible.
The Colombian peso is further compounding issues with its strength against the dollar eroding margins received with the farmers.
Coffee growers in India exporting to the European Union must now register through the Coffee Board of India’s new digital “Coffee App”. The platform has been introduced to help producers meet the requirements of the EU Deforestation Regulation (EUDR), which requires traceability and geolocation data demonstrating that coffee has not been produced on recently deforested land.
The Coffee Board says the app will centralise grower information and compliance records, helping producers maintain access to the European market while reducing reliance on third-party compliance services. The move represents a significant step in India’s efforts to strengthen traceability systems at origin and prepare its coffee sector for evolving international regulations.
Best of Rwanda 2026 Specialty Coffee Competition came to a close on Thursday 27th with K-Organics in Huye District taking the top spot with a score of 90.74 points with an anaerobic natural coffee. In a release, NAEB Chief Operations Officer, Mrs. Sandrine Urujeni, was said to have warmly welcomed the jurors to Rwanda and thanked them for accepting to contribute their expertise to the Best of Rwanda 2026 competition.
“We are delighted to welcome you to Rwanda and to have you join us for this important celebration of the excellence, passion and hard work behind Rwandan coffee. Your presence and expertise bring an important international perspective to the competition, while also providing an opportunity for you to experience Rwanda, its people and the unique story behind every cup of our coffee,” she said.
Mrs. Urujeni noted that Best of Rwanda continues to provide an important platform for showcasing exceptional coffees and connecting Rwanda’s coffee producers with the global specialty coffee market.
Coffee Market Report
This report covers the period from Monday 17th August to Friday 21st August and was written by James Duncan and Jamie Treby.
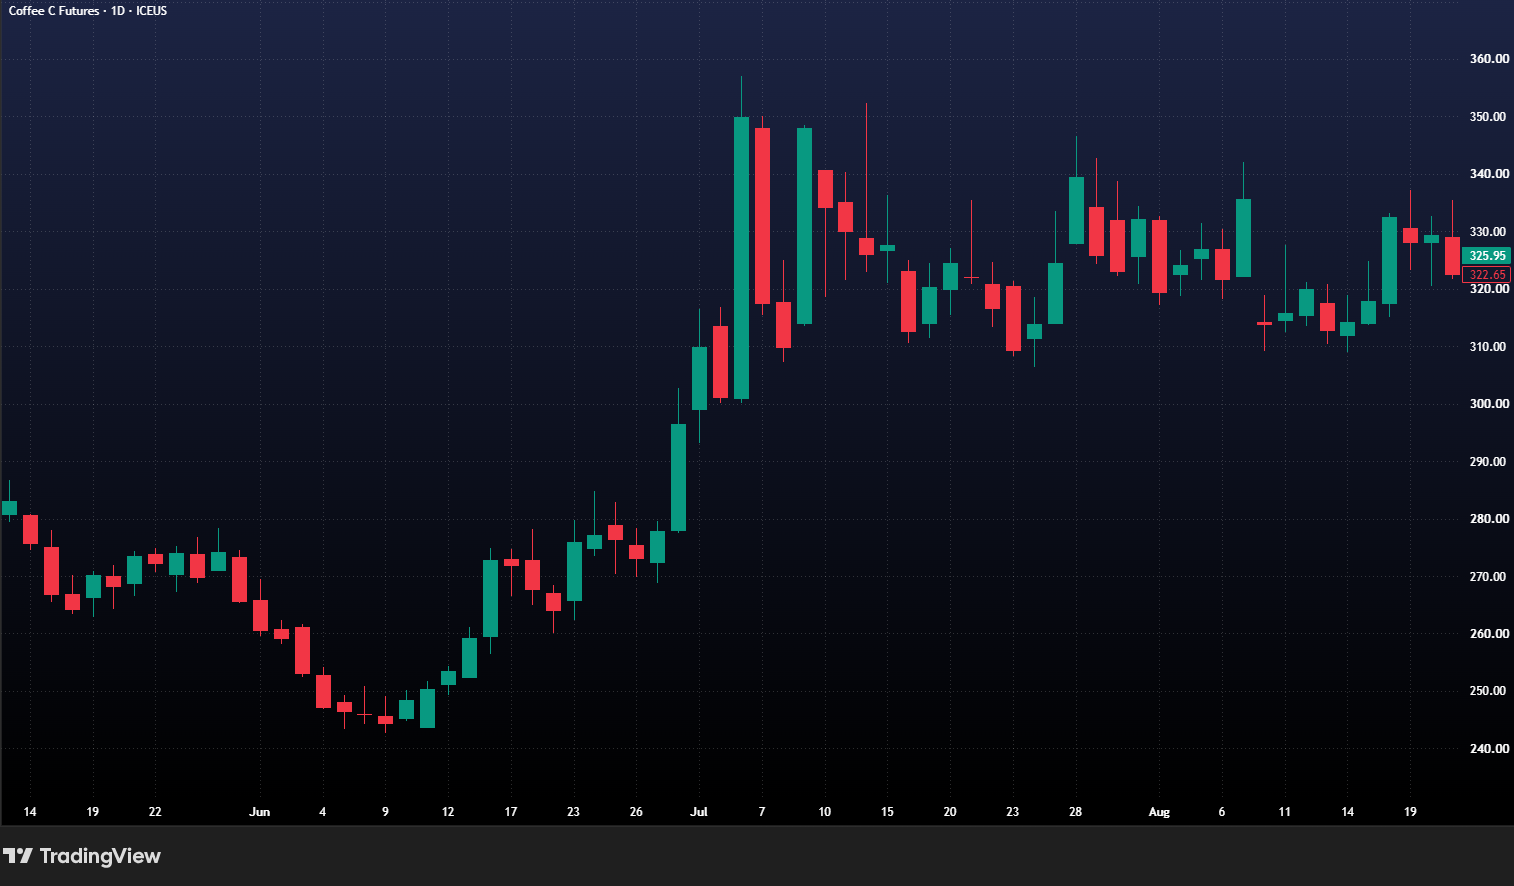 Arabica (Chart: TradingView)
Market Report
The Dec-26 terminal opened the week on 17th August just 0.10 usc/lb above the previous week’s open, at 314.20 usc/lb. Although we report on the most active terminal month (Dec-26), it is worth noting the flurry of activity on the September terminal as we drew into FND last week. With lots of open contracts still waiting to be fixed, presumably in part due to the delayed Brazil harvest, we saw much higher volumes of Sep-26 than expected as commercials fixed and rolled their position. On Monday open, the U/Z switch was already sitting at 24.3 usc/lb, which only increased to 27.2 usc/lb at close.
This momentum continued Tuesday, with 6,779 lots traded against September, 4,879 of which were U/Z switches driving both terminals up to highs of 364.25 / 333.25 usc/lb for Sep/Dec respectively – with the switch climbing to 30.95 usc/lb on market close. Wednesday and Thursday stabilised slightly, still showing signs of volatility with ranges of 13.95 and 12.20 usc/lb respectively, but closing -4.25 usc/lb and +1.10 vs previous day’s close.
After a busy week of switches and commercials squaring before FND, Friday’s volume was somewhat lower. With fewer participants in the market and no more switches, the market turned towards the fundamentals. Cooxupe reported on Wednesday that 81.1% of the harvest was complete, still below last year’s level at this time but progressing well. This provided some downwards pressure on the market which closed 6.65 usc/lb down at 322.65 – +8.45 usc/lb on week open.
 DXY (Chart: TradingView)
 GBP/USD (Chart: TradingView)
Currency & Macro
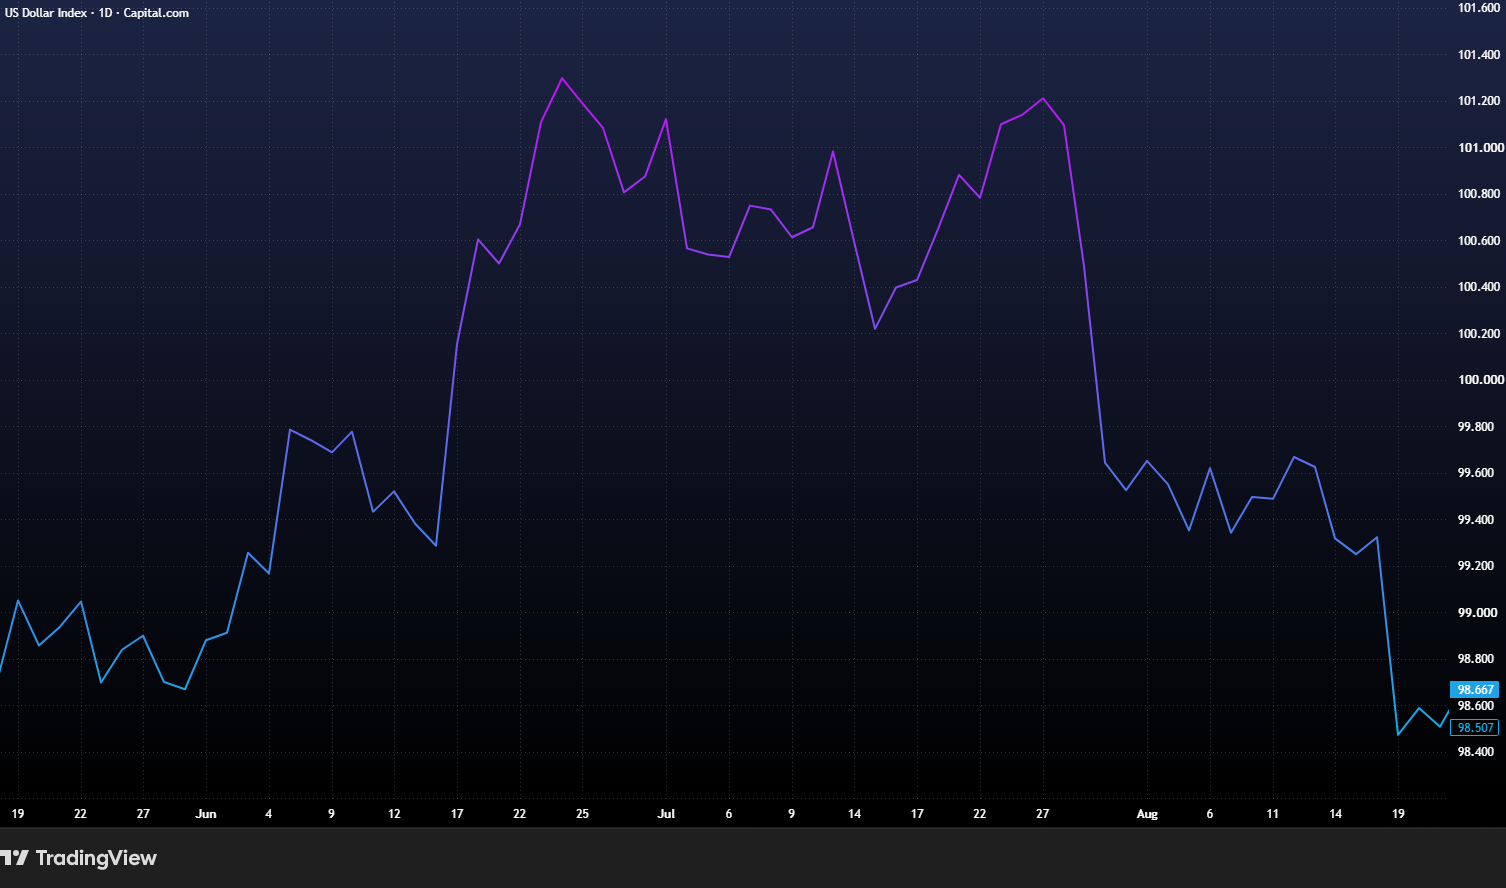
The week was mostly dominated by USD weakness, with the DXY slipping from around 99.6 to 98.5 over the course of the week. Market participants remain sceptical of the Fed’s ability to stabilise the long-term yields on the bond market. Weaker than expected employment and retail sales in the US also eroded confidence in the dollar during this period.
 EUR/USD (Chart: TradingView)
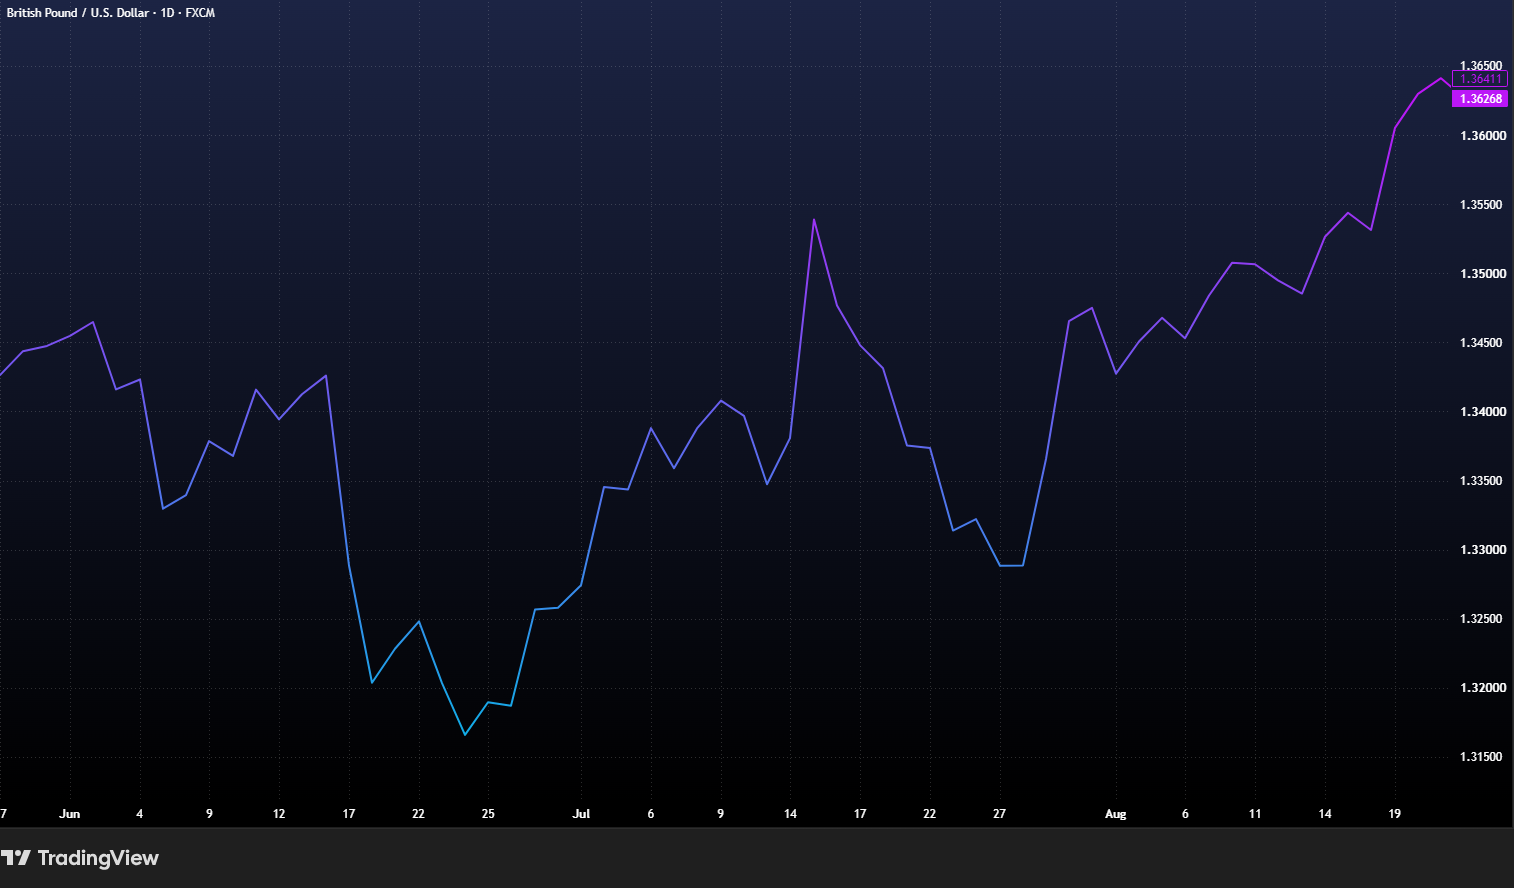
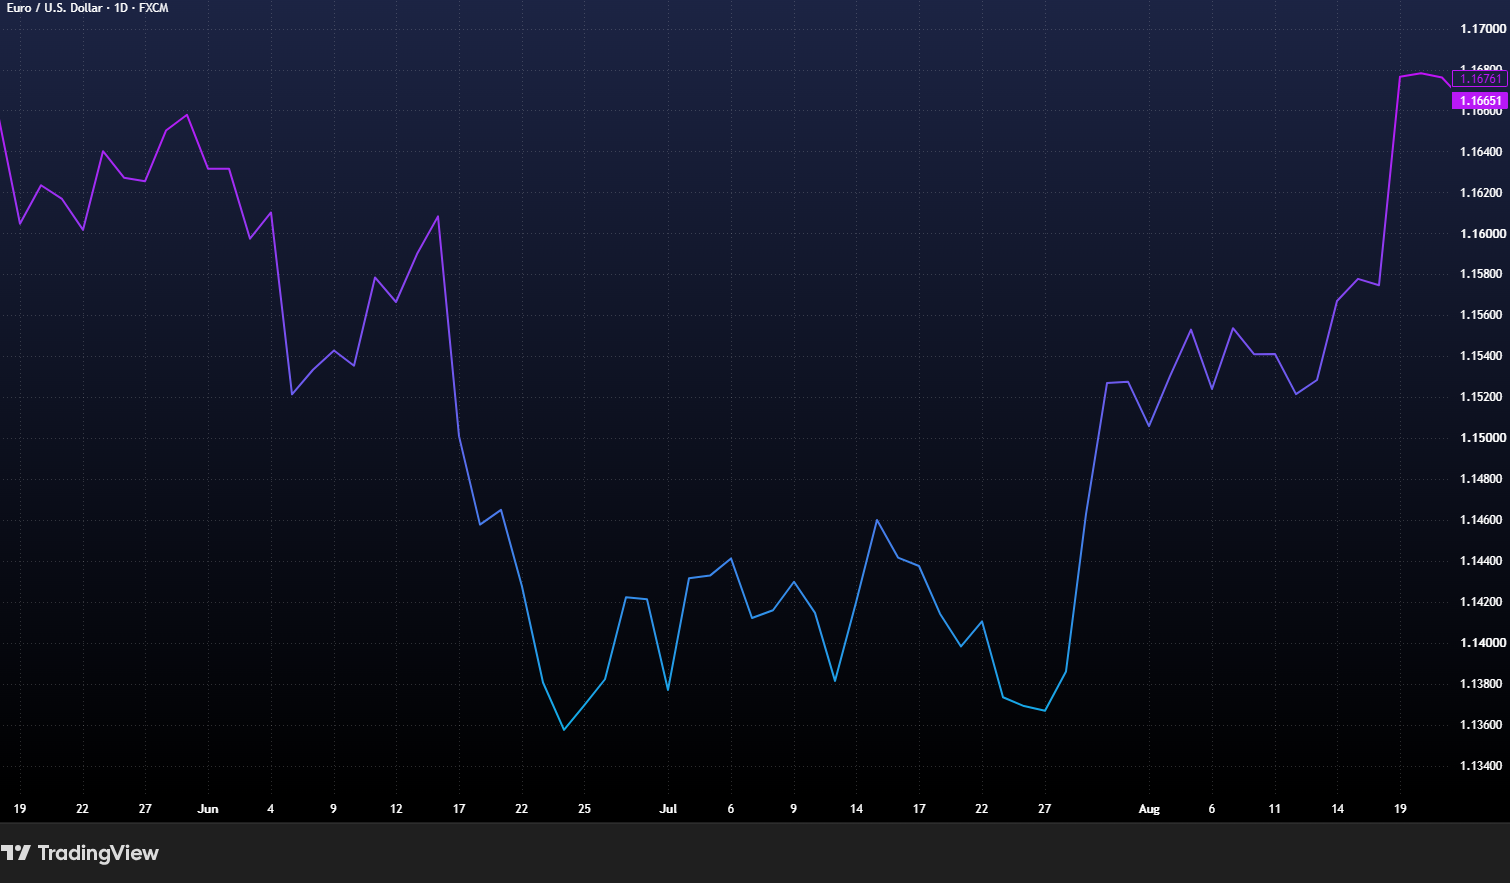
Across the pond, investors looked to the recent economic data from UK and the Eurozone which looked somewhat healthier in comparison. Although inflation did increase, this was broadly expected with knock on effect from the US-Iran conflict beginning to show. It is currently expected that both the ECB and BoE will maintain interest rates during 2026, providing some stability for these currencies. The GBP/USD pair traded above 1.36 towards the end of the week, with the EUR/USD pair making similar gains above 1.165.
Origin
Panama is intending to reduce the number of vessels passing daily through the Panama Canal from 36 to 32, it has been reported. This is due to low water levels and comes into effect in September. Whilst not a huge issue for Europe currently, with Peru and some El Salvador coffee routes potentially affected, the global market has experienced issues before. In 2023, El Nino caused the driest October on record and caused more severe cuts in passages, as the water supply is shared with the drinking water for the country.
Vietnam and Uganda have jointly announced a continuation of building links and cooperating on their coffee chains. The commitment is focusing on building resilient, deforestation free coffee and is set to last for 5 years, enhancing the cooperation between both the world’s largest Robusta producer and Africa’s largest coffee exporter by volume.
IDH, an independent international organization headquartered in Utrecht established by the Dutch government in 2009 will facilitate the partnership. Their CEO, Daan Wensing, was quoted as saying “It’s inspiring to see two of the world’s leading coffee producers coming together to secure the future of coffee farming in a rapidly changing world. This partnership sets an example for how countries can take control and make sure their farmers, and their food systems, are resilient and future-proof. This also gives private sector the confidence to invest – turning resilience from a development goal into a genuine business proposition and a core part of how coffee value chain partners do business.”
Brazil harvest is mainly over, with the focus now turning to flowering and fertilisation. CEPEA (Center for Advanced Studies on Applied Economics) have reported a welcome drop in nitrogen fertilizer costs for farmers from the May increases, though notes this is still above last year’s costs. Pruning and renovation is benefitted by the higher prices, and rainfall is expected to trigger flowering in Matas de Minas, with Cerrado and Sul de Minas being watched for this week.
Coffee Market Report
This report covers the period from Monday 10th August to Friday 14th August and was written by Hannah Wakefield and James Duncan.
 Arabica (Chart: TradingView)
Market Report
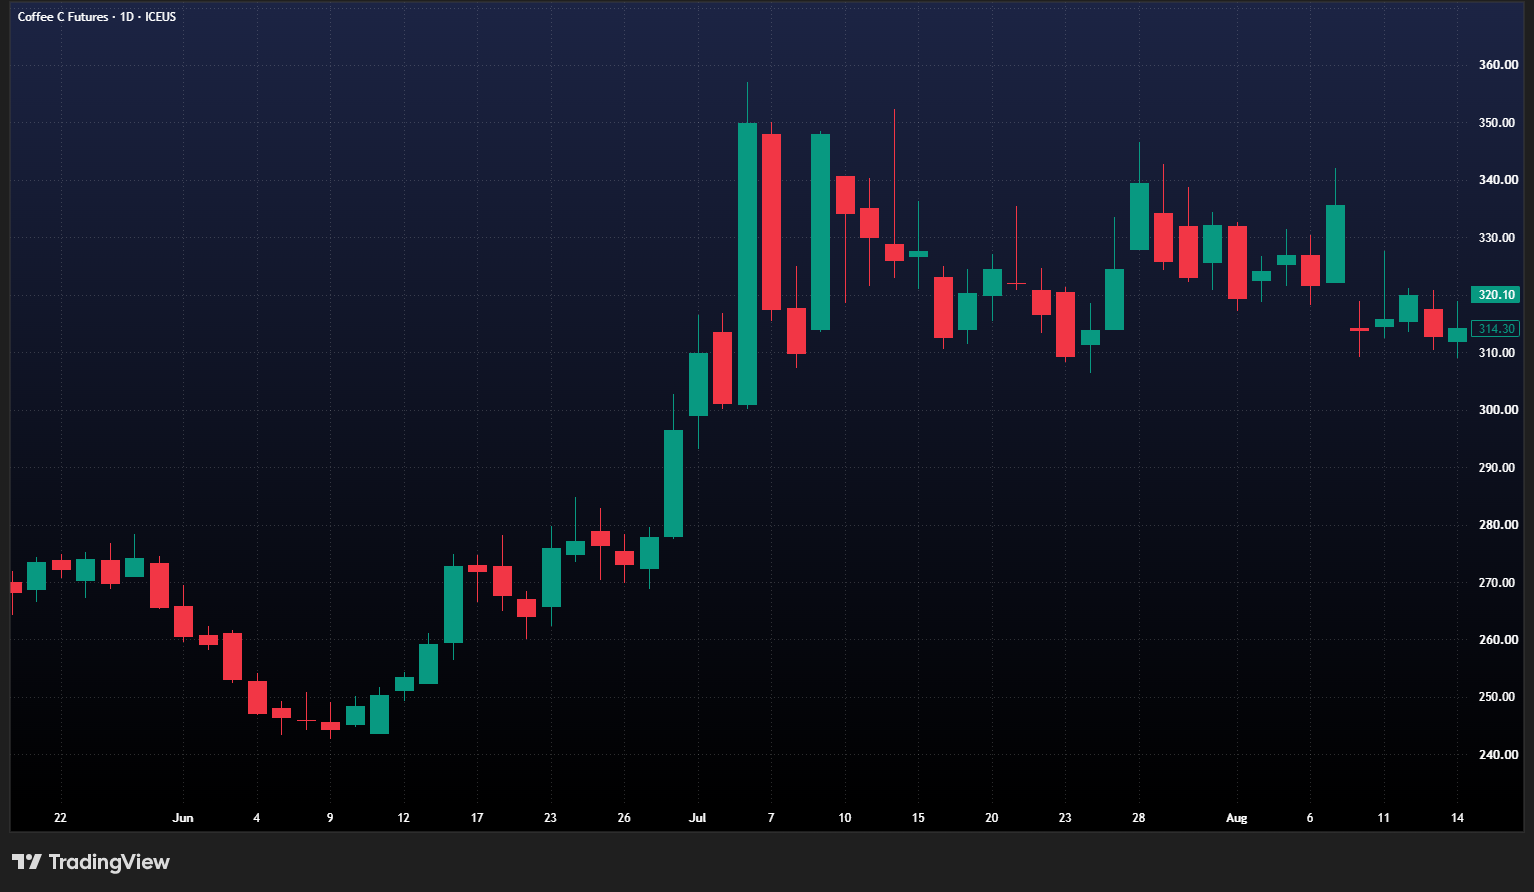
As December is now the most active terminal month, we will be reporting on the KCZ26 levels unless otherwise indicated.
Opening at 314.20, the week saw modest movements either side of this on Monday following little fundamental news. The previous week’s COT report showed that managed money reduced their net long position by 1.5k (to 23,550) as profit taking continues. After market close, certified stocks showed a rejection of 2,610 bags of Brazil which drove the market higher on Tuesday reaching 327.55 usc/lb (the week’s high) before momentum stalled and unwound almost all gains, closing at 315.70 usc/lb.
Wednesday posted modest gains of 4.25 usc/lb as the market continues to look for direction. Limited reserves of certified stocks provide good support, while Tuesday’s rejection of higher levels provides resistance. Thursday reversed direction, closing 2 usc/lb below week open (312.80 usc/lb). Reports cementing what we already knew, that the Brazil harvest is a few weeks behind last year’s, provided additional support on Friday, with the week closing slightly higher at 314.30 usc/lb, just 0.10 usc/lb above week open.
Currency & Macro
 DXY (Chart: TradingView)
Last week saw a range of economic data released from both sides of the pond. In the US, CPI eased from 3.5% to 3.4%, with core inflation cooling to 2.5%. On the flip side, retail sales for July fell 0.6%, below expectations. Taken together, there is less pressure on the Fed’s to raise interest rates in the short term.
Across the Atlantic, UK GDP grew by 0.4% in Q2 (down from 0.6% in Q1), supported mainly by the service sector, while manufacturing growth remains weak. Although this is a retraction of 0.2% vs Q1, it was widely expected that growth would stall or retract through 2026 after the US-Iran conflict, so this small decline was considered resilient. The Eurozone similarly posted 0.4% GDP growth in Q2, up from 0% in Q1. Given the conflict in the middle east, this result was even more impressive for the Eurozone.
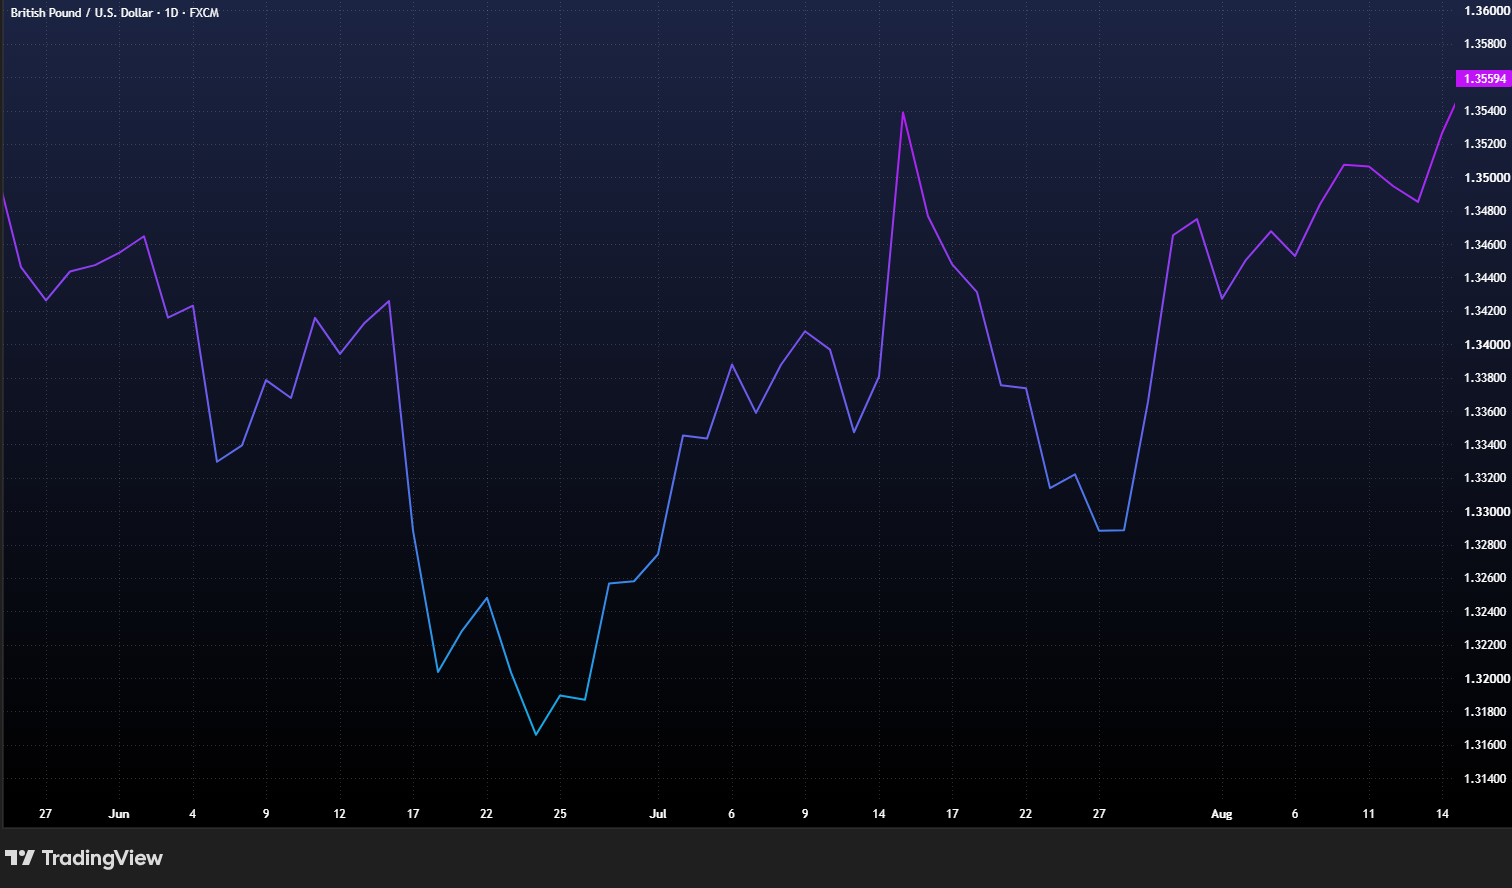
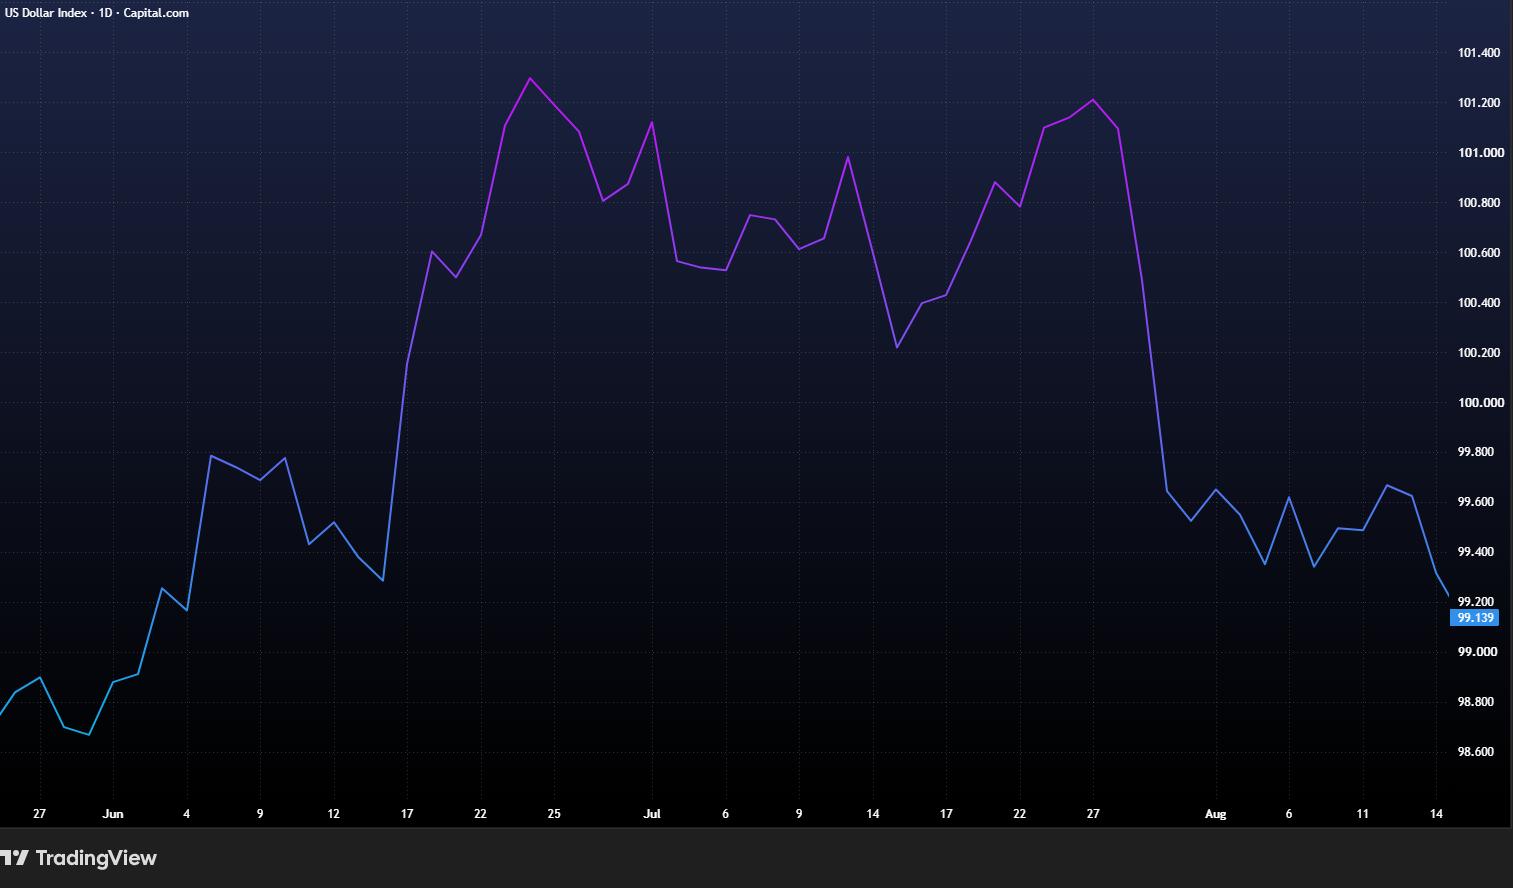
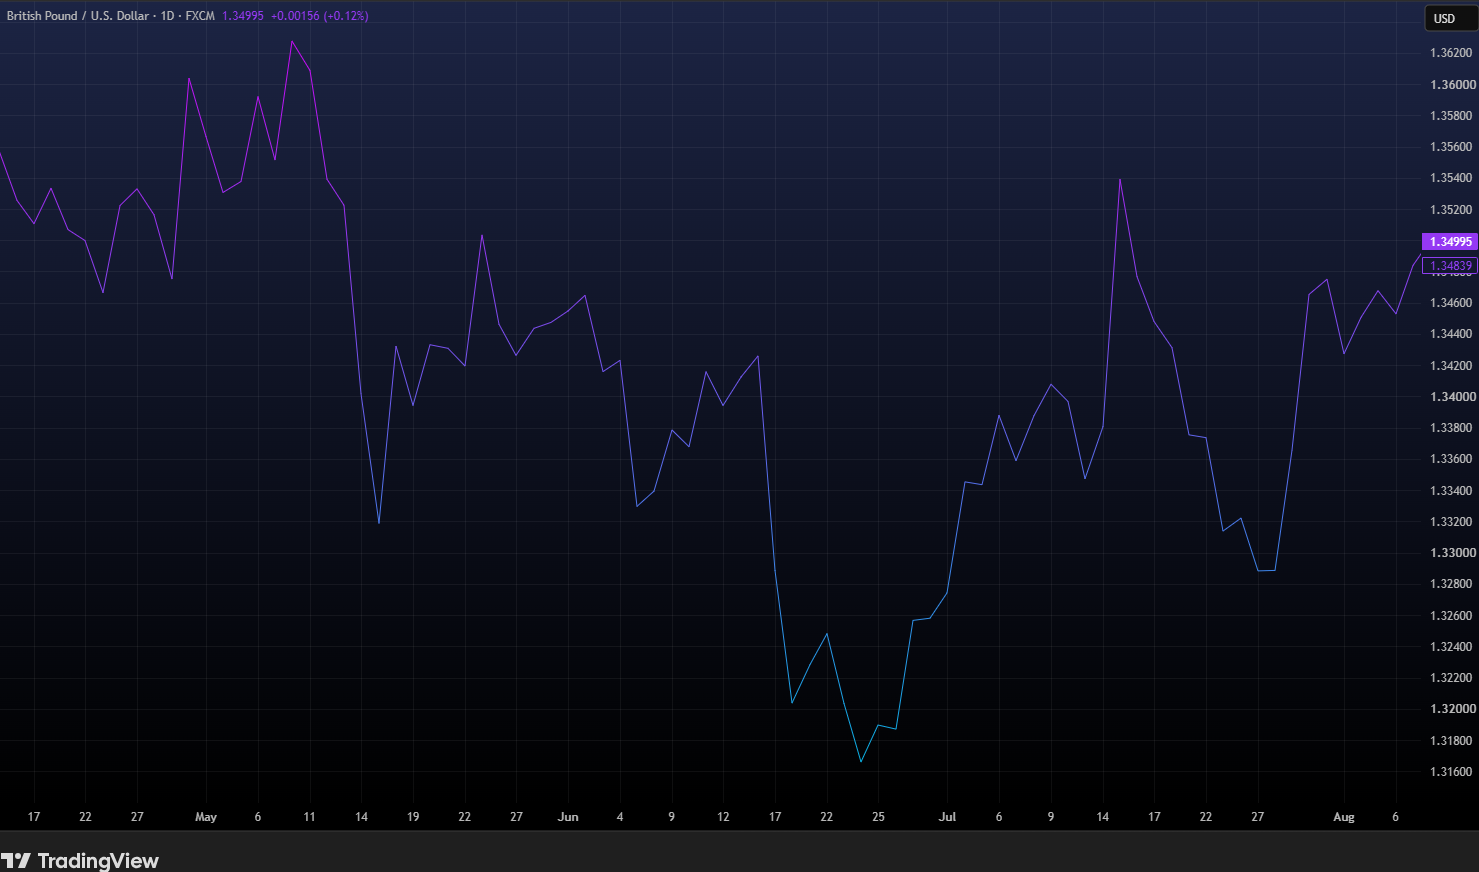
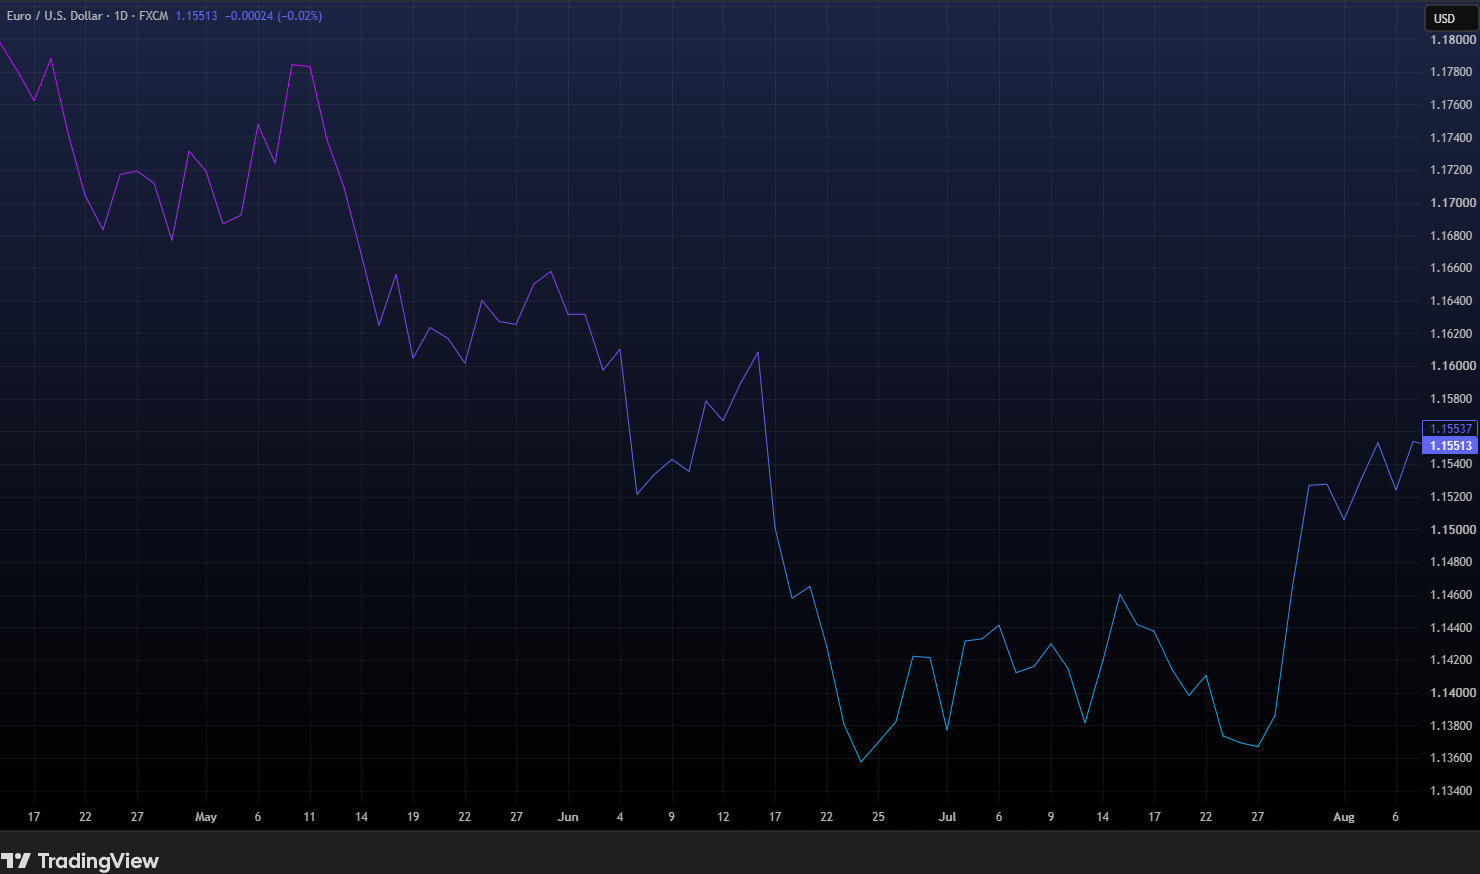
All in, the currency pairs we mainly concern ourselves with here (GBP/USD and EUR/USD) traded mostly range bound during the week, with both pairs cementing their current values around 1.350 (GBP/USD) and 1.155 (EUR/USD). The DXY during this time flirted with the 100 level but ultimately endured most of the week just below.
Origin
On Monday 10 August, the most powerful earthquake in over a century hit western Colombia, at a magnitude of 7.4 on the Richter scale. More than 250 people have been killed, and nearly 500 people unaccounted for. The quake was a ‘strike-slip earthquake’, triggered by horizontal movements of the Earth’s crust, causing a type of shaking that can cause more damage to buildings. We have been in touch with our partners in Colombia, and our thoughts remain with those affected.
The earthquake struck in the heart of Colombia’s coffee-growing regions, and the FNC have reported that farmers in the regions of Risaralda, Caldas, Valle del Cauca, Antioquia, Choco and Quindio have been affected, with homes, farms and rural infrastructure all damaged. Currently the FNC are estimating over 37,000 coffee-growing families have been impacted. Beyond local damage, the knock-on effect on logistics is being felt across the country. Finding lorries, navigating damaged roads and the temporary closure of Buenaventura port have all had an impact. Buenaventura is already shipping again, but many shipments of coffee have already been diverted to Colombia’s Caribbean ports, which will likely cause higher congestion there than usual, and delays are expected.
Exports of Arabica from Brazil remain low. In July 2026 1,818,144 bags were exported, 8.9% lower than the previous July, and the lowest volume for July since 2018. The delays are continued to be caused by rainfall interrupting the harvest and logistical bottlenecks in Brazilian ports caused by outdated infrastructure, compounding the issue, according to Marcio Ferreira, the president of Cecafe. However, Ferreira remains hopeful that exports will pick up through August and recover by the end of the year, after all they are in the middle of a bumper crop.
Coffee Market Report
This report covers the period from Monday 3rd August to Friday 7th August and was written by Hannah Wakefield.
 Arabica (Chart: TradingView)
 Robusta (Chart: TradingView)
Market Report
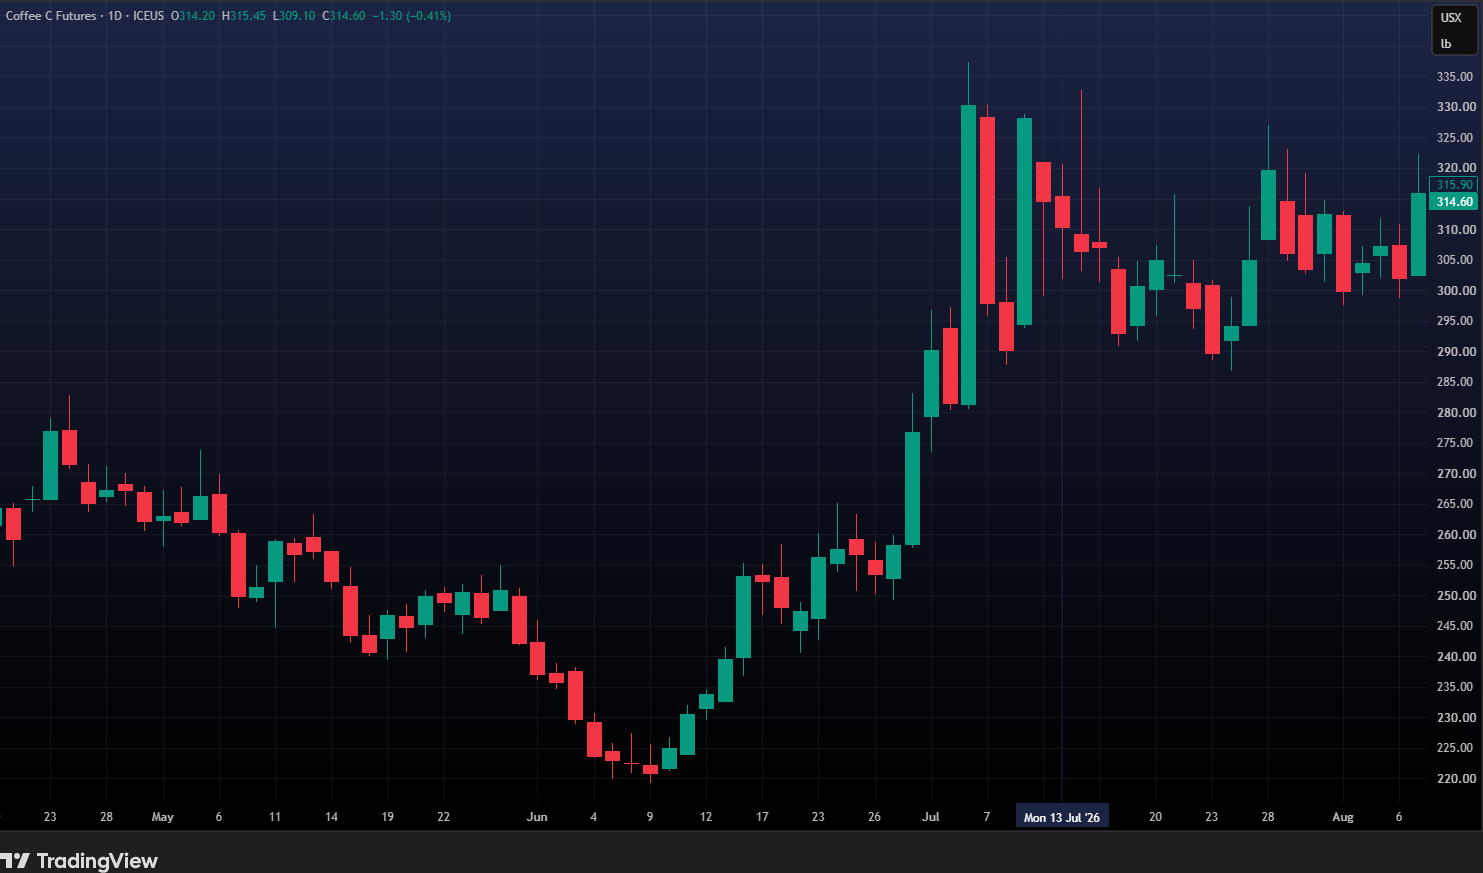
The market opened on Monday at 332.00 cl/b, close to the daily high of 332.65 c/lb. After which it fell, closing at 319.50 c/lb. Trading was mostly sideways Tuesday through Thursday, hovering around the 320 c/lb – 325 c/lb mark.
Friday was the most notable trading day. The market opened at 322.15 c/lb, and hit highs of 342.00 c/lb. This was supported by Friday’s dollar weakness, see below, as well as another drop in certified stocks. On the same day they fell to a two and a half year low of 244,172 bags. Despite the drop on Monday and spike on Friday, the week closed at 335.55 c/lb, just 3.55 c/lb higher than the week open.
Currency & Macro
 GBP/USD (Chart: TradingView)
 EUR/USD (Chart: TradingView)
On Friday 7th August the US Dollar Index (DXY) hit a 7-week low, dropping 0.41%. This was due to US July payroll data being released and showing unexpected weakness, with the US economy creating fewer jobs than expected. The payroll report also increases the chances of the Fed cutting interest rates at the next Federal Open Market Committee (FOMC). Friday also saw a rally in stocks and commodities, including coffee, which curbed liquidity demand for the USD, all of which contributed to the weakening of the US Dollar.
According to Abbas Araghchi, the Foreign Minister of Oman, a pact between Oman and Iran to open a shipping route through the Strait of Hormuz is “very close”, although it may include conditions including the US to pay compensation to Iran. Whilst this suggests some positive progress, other Iranian lawmakers have said that if the strait were to reopen, they would ban all American and Israeli ships from the waterway as part of the deal.
Origin
Between January and July 2026, coffee exports from Vietnam increased by 21.1%, compared to the same period in 2025, totalling 1.31 million MT, according to Vietnam’s National Bureau of Statistics. Over the whole of 2025, Vietnam exported 1.58 million MT of coffee, which in itself was an increase of 17.5% compared to 2024. The current crop (2025/6) is estimated to reach 1.76 million MT, which would be a 6% overall increase compared to the previous crop, and the largest crop the country has seen in four years. Figures from just July exports, also show significant increase compared to last year. This July 2.46 million bags were exported from Vietnam, 43.3% increase on July 2025. This reflects the overall increase in production and exports, but is likely supported by importers in the EU shipping earlier than usual to ensure the coffee lands in the EU and clears customs before EUDR regulations come into effect at the end of the year. Germany, Spain and Italy are some of the biggest buyers of Vietnamese coffee in the world, so if they bought earlier than usual this would certainly shift Vietnam’s monthly export figures.
In Brazil, the harvest is continuing to make progress, if slowly. As of 6th August, Cooxupe’s members had completed 67.3% of the harvest. This year’s harvest has made the slowest progress since 2018. This has largely been due to unusual rainfall and weather patterns hindering progress. The excessive rain also raises concerns about the quality of the crop as it can affect how the coffee dries, which in turn can affect the profile. If rainfall continues to be unusual, which is possible given the El Nino phenomenon, then the flowering for the next crop may be affected as well.